Most manufacturing plants track scrap and rework because those numbers are visible on the shop floor. What remains hidden is the full financial impact of quality across the entire value stream. When you only measure the waste you can physically see in bins, you miss the compliance overhead, the inspection capacity, and the warranty claims slowly eroding your margin.
I have walked through waste areas at multiple plants, including Norgren, where supervisors accepted massive scrap levels as a standard cost of doing business. Standing in one facility, I looked at bins of rejected serial production parts and asked for the financial total. The response was dismissive: that is just waste. When we finally calculated the annualised figure, it exceeded two million euros in discarded material alone. Nobody had quantified it because nobody had been asked to.
Once we mapped the total cost across all categories, the real number was roughly five million euros annually. The waste bins represented less than half the damage. Quality Cost Analysis forces an organisation to confront the true price of poor quality and provides the baseline required to shift from reactive firefighting to engineered prevention.
The Four Categories of Quality Cost
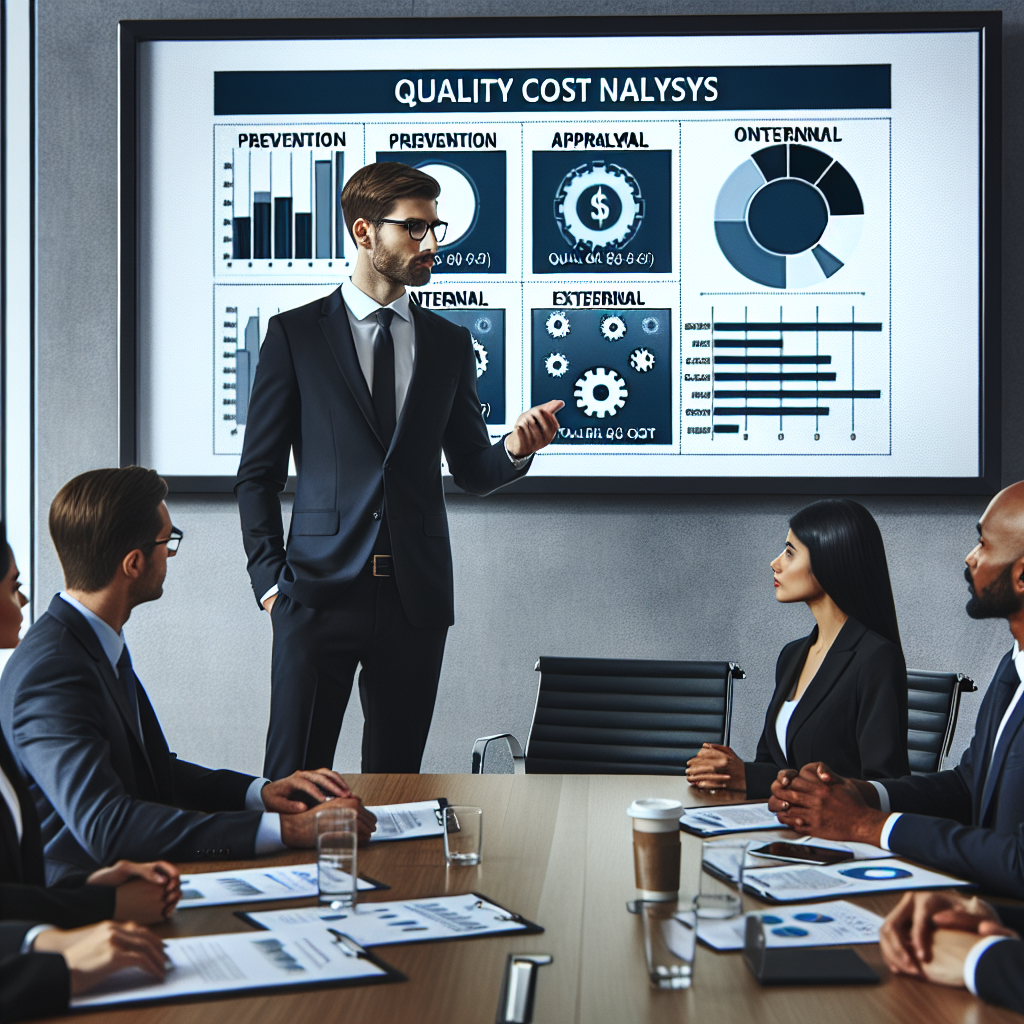
Quality Cost Analysis divides financial impact into four distinct categories. This structure prevents teams from focusing exclusively on visible scrap while ignoring the systemic costs of inadequate processes. Without this framework, improvement efforts scatter and the accounting department continues to treat quality as an unmanageable overhead rather than a controllable variable.
Prevention costs cover activities designed to stop defects before they occur. This includes quality planning, APQP documentation, employee training, supplier audits, and process validation against standards like IATF 16949 and AS9100. Appraisal costs cover the measurement and detection of defects through incoming inspection, in-process testing, final auditing, calibration, and MSA studies. Together, these two categories represent your investment in conformance.
Internal failure costs arise when defects are caught inside your facility before shipment. This includes scrap material, rework labour, re-inspection time, and downtime caused by non-conforming processes. External failure costs arise when defects reach the customer: warranty claims, returned goods, penalties, and lost business. External failures are always the most expensive category because they carry reputational damage alongside direct financial loss.
| Category | Description | Typical Focus |
|---|---|---|
| Prevention | Activities to prevent defects (Training, APQP) | Investment |
| Appraisal | Measuring and detecting defects (Testing, Audits) | Detection |
| Internal Failure | Defects caught before shipment (Scrap, Rework) | Waste |
| External Failure | Defects reaching the customer (Warranty, Returns) | Loss |
Diagnosing the Cost Distribution
The power of Quality Cost Analysis lies in the ratio between these four categories. A plant spending less than five percent of its total quality cost on prevention will almost always spend over eighty percent on internal and external failure. That imbalance signals a reactive culture where resources are consumed by correction rather than engineering.
When prevention investment rises above twenty percent of the total, failure costs drop sharply. This is not theoretical: the relationship holds across automotive, aerospace, and industrial manufacturing. Plants with mature quality systems operate at a total cost of quality between two and four percent of turnover. Reactive plants operate at five to ten percent, burning cash on avoidable defects.
Cost of Quality Distribution Thresholds
Restructuring Internal Failure Costs
Internal failure is where most plants find their largest immediate savings. In my experience leading quality transformations, scrap and rework consistently account for over eighty percent of internal failure costs. The remaining balance goes to re-inspection, machine downtime during non-conformance investigations, and productivity losses from running degraded processes.
Reducing these costs requires disciplined root cause analysis rather than additional inspection. Implementing structured 8D methodology, 5-Why analysis, and fishbone diagnostics forces engineering teams to address the underlying process failure. When you pair this with Lean manufacturing tools like 5S, SMED, and TPM, the process stabilises and the defect rate drops predictably.
At one automotive plant, structured root cause analysis and process standardisation reduced scrap from one point two million euros to three hundred thousand within twenty-four months. Rework dropped by seventy-five percent. Re-inspection was eliminated entirely because the processes generating non-conformances had been corrected at the engineering level rather than patched on the floor.
The mechanism is straightforward. Stable processes produce conforming parts. Conforming parts do not require sorting, rework, or scrap documentation. Every hour of engineering effort invested in process capability returns multiple hours of recovered production capacity that would otherwise be lost to containment activities.
Eliminating External Failure Through Upstream Action
External failure costs are the most damaging category because they include customer complaints, warranty claims, returned shipments, and contractual penalties. At the Norgren plant, external failures initially totalled two million euros annually. The root causes were rarely mysterious: they traced back to process variations that internal inspection had failed to catch.
Cutting external failure requires two parallel actions. First, you must tighten internal detection through SPC on critical parameters and capable measurement systems validated by MSA. Second, you must close the feedback loop with customers through a formal complaint system that feeds every field return directly into corrective action. Without this loop, warranty data remains a financial statistic rather than an engineering input.
External failures are not quality problems. They are engineering problems that survived your inspection process.
When these mechanisms are in place, external failure costs collapse. Within twenty-four months at that same facility, complaint costs dropped by nearly ninety percent and warranty costs fell by over ninety percent. Customer churn driven by quality issues was eliminated. The remaining external failure budget shrank to one hundred and fifty thousand euros, a fraction of the original burden.
Implementation: Building a Cost of Quality System
Implementing Quality Cost Analysis requires cross-functional data collection that most plants have never attempted. Finance holds the warranty and penalty figures. Production holds the scrap and downtime data. Quality holds the inspection and complaint records. Sales holds the customer return information. None of these departments will voluntarily consolidate this data; the quality function must drive it.
Quality Cost Analysis Implementation Cycle
- 01Define categoriesMap every quality-related expense in the general ledger to one of the four standard categories.
- 02Collect dataPull figures from finance, production, quality, and sales to build the complete cost picture.
- 03Analyse and prioritiseUse Pareto charts to identify which failure modes drive the largest financial losses.
- 04Implement countermeasuresShift budget from detection and correction into targeted prevention activities.
- 05Monitor monthlyTrack the ratio of prevention to failure costs and verify the total quality cost is declining.
The first analysis is always the hardest because it exposes numbers that plant managers have been working around for years. The instinct is to argue with the data or dispute the categorisation. Resist that. The goal of the baseline is accuracy, not comfort. Once the baseline is established, monthly tracking takes minimal effort and the trend lines become the most powerful improvement metric in the plant.
Prevention ROI in Practice
The financial case for prevention investment is consistent across every plant I have audited and improved. At an ArcelorMittal line producing steel sheet, scrap was running at fifteen percent of output. The team invested three hundred thousand euros in targeted prevention: operator training, process planning, and supplier quality programmes. Within twelve months, scrap dropped to three percent, saving one point two million euros annually.
That is a four hundred percent return on investment in a single year. The mechanism was not complex. Training addressed operator-induced variation. APQP methodology caught design issues before they reached serial production. Supplier audits reduced incoming material defects. Each prevention activity removed a specific failure mode from the process.
Reactive vs Prevention-Focused Quality Cultures
Reactive plant behaviour
- Prevention under 5% of quality budget
- Failure costs exceed 80% of total spend
- Quality treated as inspection and sorting
- Total quality cost runs 5-10% of turnover
Prevention-focused approach
- Prevention above 20% of quality budget
- Failure costs driven below 40% of total
- Quality engineered into the process upstream
- Total quality cost reduced to 2-4% of turnover
Six Sigma DMAIC methodology operationalises this same principle. Each sigma level improvement reduces the defect rate by an order of magnitude, and total quality cost drops by five to ten percent per sigma shift. Moving from three sigma to four sigma cuts defects from roughly seven percent to under one percent. The financial impact compounds because you are eliminating failure modes permanently, not containing them.
Quality Cost Analysis is not an accounting exercise. It is an engineering tool that exposes where your processes are bleeding and measures whether your countermeasures are working. The plants that embrace it move from reactive containment to proactive engineering. Those that ignore it continue to pay for the same defects year after year, buried in the cost of doing business.