Quality costs are the total expenditure required to ensure conformance and the financial penalty incurred when a process fails. In manufacturing, these costs frequently consume ten to fifteen percent of total revenue. Most plant managers accept scrap, rework, and warranty claims as unavoidable operational friction. They are not. They are the visible symptoms of underfunded prevention.
I encountered this directly at an automotive supplier manufacturing axles for commercial vehicles. The plant was operating with quality costs at fifteen percent of turnover. The CFO demanded cuts across the quality department. Cutting inspection or training yields immediate monthly savings, but it destabilises the process and multiplies external failures within two quarters. The objective is not to reduce the quality budget. The objective is to change the ratio.
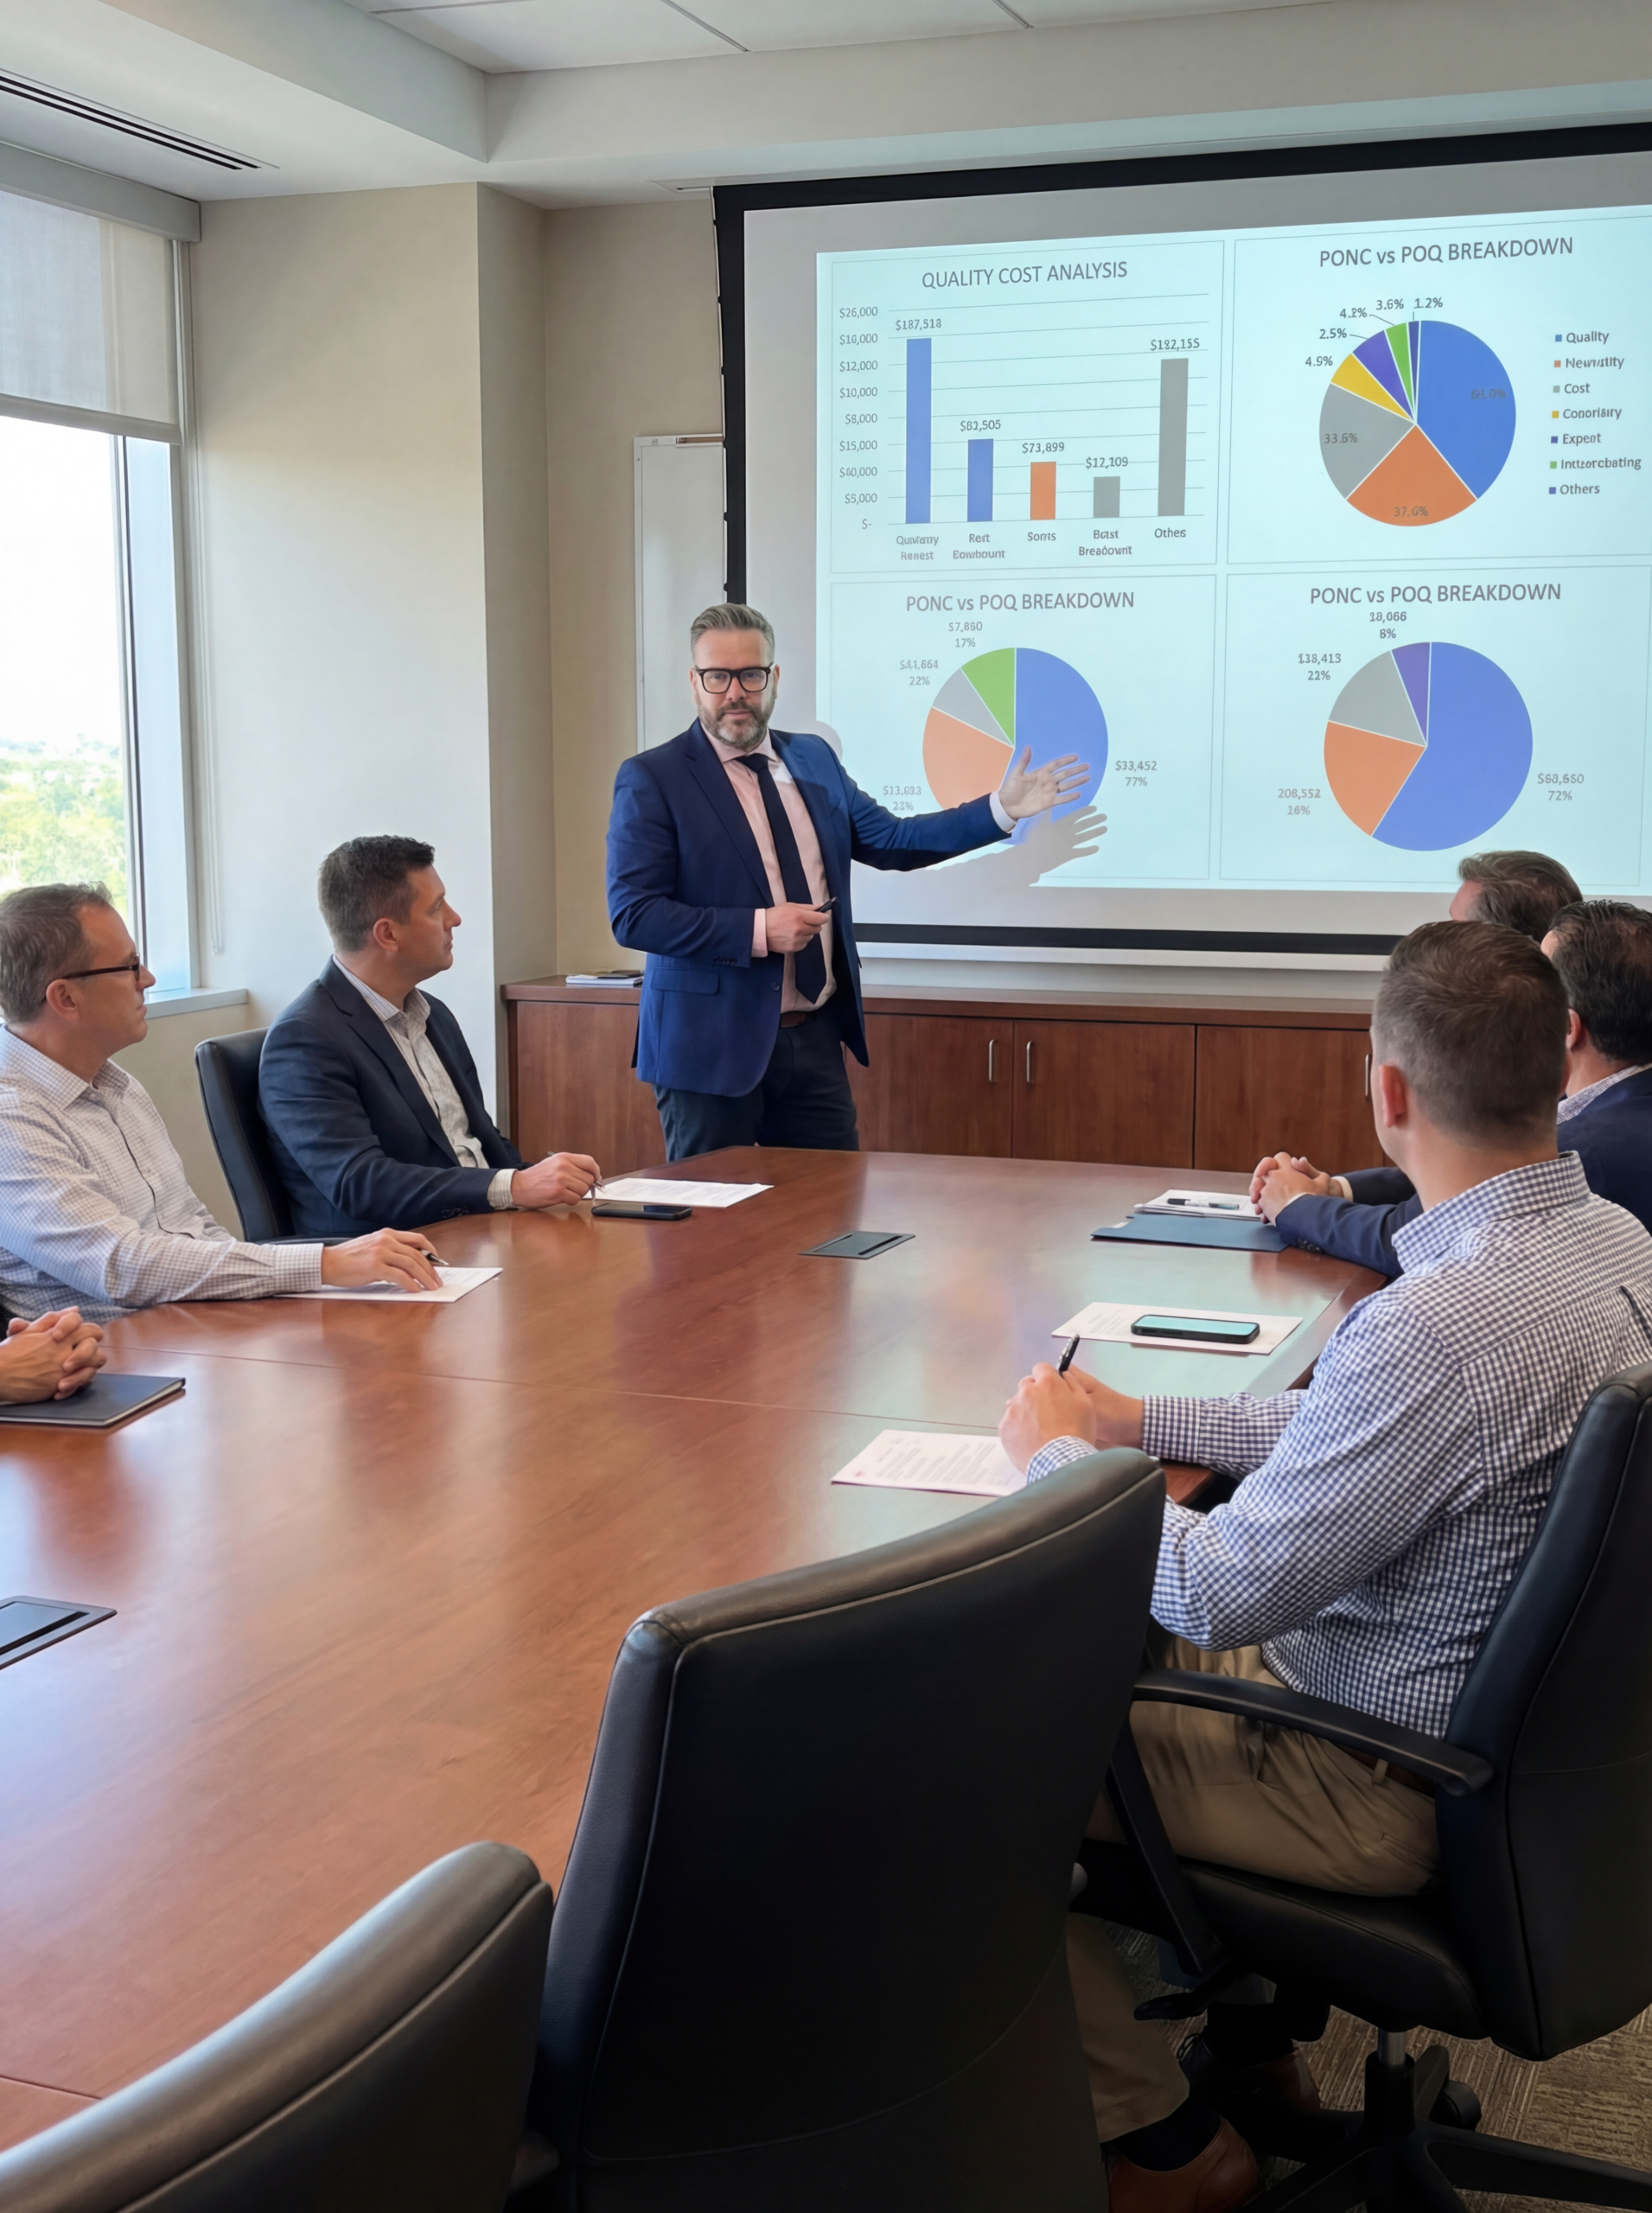
Quality Cost Analysis uses the Prevention, Appraisal, Failure (PAF) model to map expenditure. By categorising every euro spent on quality, you identify exactly where investment reduces downstream waste. This analysis shifts the financial argument from subjective quality rhetoric to hard data that a CFO cannot dispute.
Categorising Expenditure Using the PAF Model
The PAF model divides quality costs into two distinct financial buckets: the Price of Quality (POQ) and the Price of Non-Conformance (PONC). POQ is your active investment in getting the product right the first time. PONC is the financial penalty of getting it wrong. Effective management requires maximising POQ to eliminate PONC.
POQ consists of Prevention and Appraisal costs. Prevention includes APQP, PFMEA, supplier qualification, and operator training. Appraisal covers inspection, testing, MSA studies, and internal audits. These are controllable investments. You decide how much capital to deploy upstream based on your risk profile.
PONC encompasses Internal and External Failure. Internal failure costs accrue before the product leaves the facility: scrap material, rework labour, and downtime. External failure costs accrue after shipment: warranty claims, 8D investigations, logistics returns, and lost revenue. External failure is the most destructive category because it erodes customer trust alongside margin.
The PAF Model Breakdown
Price of Quality (Investment)
- Prevention: APQP, PFMEA, training, SPC deployment
- Appraisal: MSA, incoming inspection, laboratory testing
- Characteristics: Planned, budgeted, directly controllable
- Goal: Increase proportion to stabilise processes
Price of Non-Conformance (Waste)
- Internal: Scrap, rework, machine downtime, line stoppage
- External: Warranty claims, field returns, lost sales
- Characteristics: Unplanned, drains margin, destroys trust
- Goal: Drive towards zero through targeted prevention
Defining the Ideal Cost Ratio
Standard accounting treats all quality costs equally. Quality engineering does not. A plant spending five percent of revenue purely on external failures is in crisis. A plant spending five percent on prevention and appraisal is world-class. The absolute number matters less than the distribution of the spend.
In a mature manufacturing operation, Prevention should consume fifty to sixty percent of the total quality budget. Appraisal requires another twenty to thirty percent. This leaves internal failure at ten to twenty percent and external failure below five percent. If your external failure ratio exceeds twenty percent, you are executing a reactive firefighting strategy, not quality control.
The overarching target for quality costs is below ten percent of turnover. Operations between ten and fifteen percent are average but vulnerable. Above fifteen percent indicates systemic process failure. The mathematical reality is that you cannot inspect quality into a product. You must engineer it through the process.
Calculating and Tracking Total Quality Costs
Implementing Quality Cost Analysis requires extracting data from existing systems. Most ERP platforms already capture these figures, but they are scattered across cost centres. Scrap is logged in production variances. Rework hides in labour hours. Warranty claims sit in customer service budgets. You must aggregate them.
Begin by mapping every quality-related general ledger code to one of the four PAF categories. Calculate the total quality cost and divide it by plant revenue. This baseline percentage dictates your strategy. If the baseline is fifteen percent, immediate intervention is required. If it is eight percent, targeted optimisation is appropriate.
You must track this metric monthly. Quarterly reviews obscure the impact of process changes. A Cpk improvement on a critical machining station takes four to six weeks to reflect in reduced scrap. Monthly trend lines provide the evidence needed to justify sustained prevention budgets to executive management.
Quality Cost Health Indicators
The Mechanism of Cost Transformation
Shifting the cost ratio demands targeted interventions. Reviewing existing PFMEA documents for all critical processes is the first step. In the axle manufacturing scenario, a structured review identified twenty-three unmitigated risks. Implementing twelve specific preventive controls cost thirty thousand euros but immediately reduced external failures by ten percent through enhanced process stability.
Process capability is the next lever. Analyse critical-to-quality (CTQ) parameters and calculate the Cpk. During the axle programme, Cpk on key turning operations averaged 1.2. Implementing Statistical Process Control (SPC) across fifteen high-impact stations and training operators on reaction plans raised the average Cpk to 1.6. This cost forty thousand euros and cut internal failure costs by forty percent.
You cannot reduce quality costs by cutting the quality budget. You change the ratio.
Supplier quality directly dictates internal and external failure rates. Audit the highest-risk suppliers, implement scorecards, and tighten incoming inspection criteria based on historical defect data. Working intensively with the three worst-performing suppliers cost fifty thousand euros in engineering time but reduced external component failures by an additional thirty percent.
Finally, systematise root cause analysis. Mandate 8D methodology for all critical customer complaints. Train the engineering team on 5 Whys and ensure corrective actions feed back into the PFMEA. Closing the loop between field failure and process design ensures the same defect does not recur, driving long-term external failure costs down.
Measuring Return on Investment
Restructuring quality costs requires upfront capital. In the axle manufacturing example, the total prevention investment increased by one hundred thousand euros over twelve months. The immediate first-year return was modest in absolute terms, with total quality costs dropping by roughly fifty-four thousand euros. The mathematical breakthrough occurs in the second year.
As preventive controls mature and process capability stabilises, failure costs plummet exponentially. By the end of the second year, internal failure costs dropped by an additional thirty thousand euros, and external failure costs halved again. Customer complaints fell from forty-eight per week to six. Warranty claims dropped from thirty-six per week to three. Customer satisfaction scores rose from 3.2 to 4.5 out of five.
The net financial impact of this structural shift includes the direct savings on scrap and rework, plus the recovered revenue from retained business and reduced warranty logistics. The programme yielded a two-hundred-thousand-euro annual saving against a one-hundred-thousand-euro prevention investment. This represents a return on investment exceeding two hundred percent in the first operational cycle.
Common Failures in Quality Accounting
The most frequent analytical error is ignoring hidden costs. Accounting systems easily capture scrap material and rework labour. They miss the expedited freight required to replace defective lots, the engineering hours spent investigating customer escapes, and the lost revenue from disqualified bids. These invisible failures often exceed the visible PONC.
Teams frequently mistake a good ratio for good absolute numbers. A total quality cost of five percent looks excellent until you realise the plant operates on a twenty-percent gross margin. If the absolute euro value of your failures threatens capital expenditure, the percentage is irrelevant. Always review the hard financial figures alongside the ratios.
Do not accept appraisal as a permanent fix. Sorting operations and one-hundred-percent end-of-line inspection mask process instability. If your appraisal costs exceed prevention costs, you are paying to find defects you already produced. Redirect that capital into engineering changes that eliminate the variation at the source.
Quality Cost Analysis fails when it lacks continuous tracking. Conducting a single baseline study identifies opportunities, but without monthly updates, management cannot verify the effectiveness of the interventions. Implement a dashboard that reports the four PAF categories, the total percentage of revenue, and the Cpk of critical processes.